What does your half-hourly data say?
A domestic decision can be made on an annual consumption total. A commercial one cannot. What matters is the shape of demand across the working day and across the year: when you draw hardest, what your overnight base load is, and how much of the middle of the day you are actually occupying. If your meter records half-hourly data, ask your supplier for it and get it before anyone designs anything. A proposal built on an annual kilowatt-hour total is a guess wearing a spreadsheet.
Does your load profile match the generation profile?
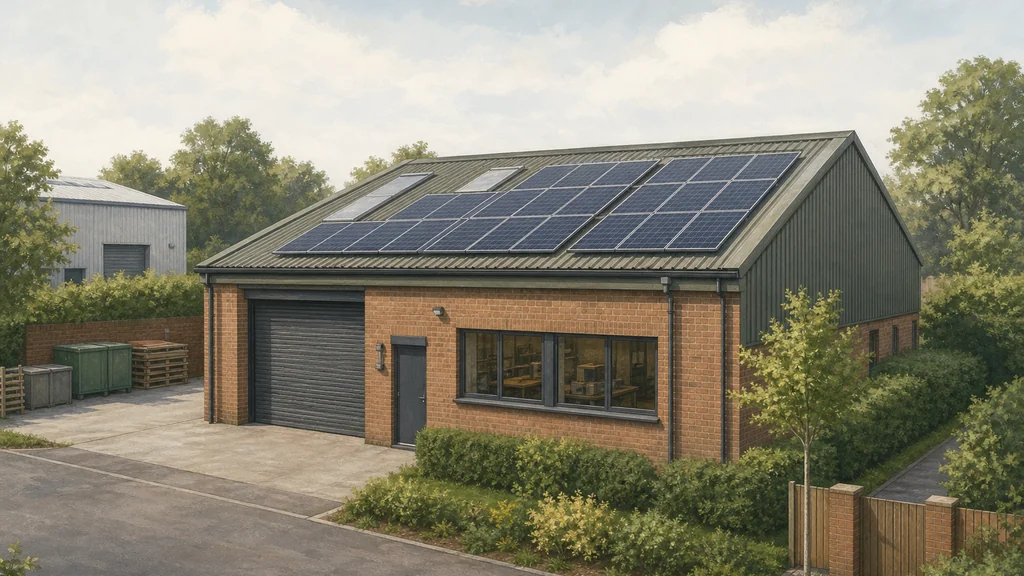
Electricity you generate and use yourself displaces electricity you would have bought. Electricity you export earns whatever your export tariff pays, which is a different and generally much smaller number. So the value of a commercial array is set by the proportion of its output you consume on site. A single-shift weekday operation, a seven-day operation and an office that empties at four o'clock produce three completely different answers from the same roof.
Capital, or somebody else's capital?
Buying outright, leasing the equipment, and a power purchase agreement where a third party owns the system on your roof and sells you the output are three different propositions with three different balance-sheet and contractual consequences. None of them is automatically right. What they have in common is that the contract, not the technology, is where the risk sits, so read it, and have your own adviser read it.
Do you own the building, and for how much longer?
Remaining lease term, landlord consent, reinstatement obligations at the end of the term, roof loading and who owns the roof itself all have to be settled before the engineering matters. If you are the landlord rather than the occupier, note that since 1 April 2023 the minimum energy efficiency standard has applied to all privately rented non-domestic property in England and Wales, not only to new lettings, so a let building at EPC F or G cannot continue to be let unless a valid exemption is registered. One of the registered exemptions exists precisely because third-party consent could not be obtained, which tells you how often that is the blocker. Source: DESNZ, "Non-domestic private rented property: minimum energy efficiency standard, landlord guidance", sections 1 and 4, last updated 5 May 2026. Checked 19 August 2026. https://www.gov.uk/guidance/non-domestic-private-rented-property-minimum-energy-efficiency-standard-landlord-guidance
Does anything have to be reported?
Two separate regimes catch larger organisations and neither is optional. Streamlined Energy and Carbon Reporting requires UK quoted companies, large unquoted companies incorporated in the UK and large limited liability partnerships to disclose energy use and greenhouse gas emissions in the directors' report. Separately, the Energy Savings Opportunity Scheme is a mandatory energy assessment scheme, administered by the Environment Agency, under which qualifying large undertakings must carry out an assessment every four years; the Phase 4 compliance deadline is 5 December 2027. A large undertaking, for the last qualification date, meant one employing 250 or more people, or with turnover above £44 million and a balance sheet total above £38 million. If either applies to you, generation is a reporting question as well as a cost question, and the two should be scoped together rather than sequentially. Sources: DESNZ, Defra and BEIS, "Environmental reporting guidelines: including Streamlined Energy and Carbon Reporting requirements", checked 19 August 2026, https://www.gov.uk/government/publications/environmental-reporting-guidelines-including-mandatory-greenhouse-gas-emissions-reporting-guidance; DESNZ and Environment Agency, "Energy Savings Opportunity Scheme (ESOS)", last updated 16 February 2026, checked 19 August 2026, https://www.gov.uk/guidance/energy-savings-opportunity-scheme-esos
And the one everybody gets wrong: VAT.
The zero rate on installing energy-saving materials, which includes solar panels and battery storage, applies to installations in residential accommodation and in buildings used solely for a relevant charitable purpose. A commercial building is neither. The relief is also time-limited: it runs to 31 March 2027, after which these installations revert to the reduced rate of 5 per cent in qualifying buildings. Note the edge cases, because they catch people both ways: self-catering holiday accommodation counts as residential accommodation, while hotels, inns and similar establishments are standard-rated. If a quotation you are given assumes zero-rated VAT on a commercial building, ask why. Your accountant should confirm the position before you rely on it. Source: HMRC, "Energy-saving materials and heating equipment (VAT Notice 708/6)", sections 2.1, 2.7, 2.21 and 2.22, last updated 31 January 2024. Checked 19 August 2026. https://www.gov.uk/guidance/vat-on-energy-saving-materials-and-heating-equipment-notice-7086